Water, Fire & Storm Restoration · San Antonio
Water Damage Restoration in San Antonio — Extraction to Final Paint, One Contractor
Licensed and insured GC handling the full loss: water extraction, structural drying, demo, and complete rebuild. Your carrier has an adjuster working to pay less — we fight to get your claim paid for what it truly takes to make you whole.
One contract, mitigation through rebuild: Single-Contract Restoration.
We Fight Your Claim
Our in-house insurance department documents the full loss and pushes your carrier to pay for what it truly takes to make you whole.
DocuSketch Every Loss
A full 3D scan and measured floor plan of your property — hidden and secondary damage on the record before demo starts.
Mitigation + Rebuild In-House
Extraction and drying through final paint — one crew, no handoff between contractors.
Licensed & Insured GC
Serving San Antonio since 2010. General Liability and Workers' Comp — certificates available on request.
No handoff between dry-out and rebuild
Most restoration companies do the mitigation — extraction, drying, demo — and then hand you a dried-out shell and a list of rebuild contractors. Most general contractors won't touch wet demo at all. Raging Bull does both. The crew that dries your structure is the same licensed and insured GC that rebuilds it, so there's one accountable contact from the first walkthrough to the last coat of paint — and no gap between dry-out and rebuild where your project sits idle waiting on a second contractor. This isn't theory: recent work includes a $5,600 emergency extraction with fans and dehumidifiers on site, plus thousands more in water-damage rebuilds across San Antonio in recent months.
Emergency? Call (512) 665-1073 now.
Water, fire, and storm — mitigation through rebuild
Every loss gets the same treatment: document it, dry it, demo what can't be saved, and rebuild it to remodel-grade finish — under one roof.
Water Damage
Water extraction, structural drying, demo of wet materials, and moisture control. We verify with moisture readings — not guesswork — before anything gets closed back up.
Fire & Smoke
Demo of fire-damaged materials, removal of odor-affected materials, and full rebuild of framing, drywall, paint, flooring, and cabinets.
Storm & Roof Leaks
Interior water intrusion from storm and roof failures — ceiling and drywall repair, with tarp-to-rebuild coordination so the hole in the roof and the hole in the ceiling get fixed on one plan.
Full Reconstruction
Drywall, texture matching, paint, flooring, tile, cabinets, and trim — remodel-grade finishes on restoration timelines, from the same GC that does this for a living.
Three water losses that work differently
Same company, same single contract — but the first day on site looks nothing alike.
Storm Damage Restoration
Roof leaks, hail-opened roofs, wind-driven rain at windows, and the frozen-pipe bursts that show up after a hard freeze.
See how we handle it →Sewage Backup Cleanup
Category 3 water. Contaminated porous materials come out rather than getting dried in place, then the room gets rebuilt.
See how we handle it →Slab Leak Water Damage
The half after the plumber: moisture mapped room by room, subfloor dried, flooring and cabinets rebuilt, claim documented.
See how we handle it →From first walkthrough to closed claim
Assess & Document
Walkthrough, photo documentation, and a written Xactimate estimate — the format adjusters expect — before demo starts.
Mitigate
Water extraction, structural drying, and demo of unsalvageable materials. Moisture readings verify dry before we move on.
Rebuild
The same licensed GC crew rebuilds — framing, drywall, paint, flooring, cabinets. No handoff, no gap, no second contractor to chase.
Fight & Close the Claim
We DocuSketch the loss, submit supplements for hidden damage, and push your carrier for the full scope — then hand you a home restored and a claim paid right.
Thank you for your outstanding work resolving the plumbing issue and water damage at our home in Cibolo, TX. … Having a single contractor seamlessly manage everything—from setting up the drying equipment and providing a same-day Xactimate estimate to guiding us through the insurance claim and completing the final restoration—made a stressful situation much easier.
In-house Xactimate, and one contractor to the last coat of paint
Everything else on this page is work any good restoration company should do. These two are the ones that change what your claim pays and how long your house sits open.
We write the estimate ourselves, in Xactimate
Xactimate is the estimating platform the insurance industry works in — line-item codes, regional unit pricing, the format an adjuster reads every day. We write our scope in it in-house, which means your adjuster and our project manager are comparing the same line items instead of translating between two documents. When a scope disagreement comes up, it comes down to a specific line item and a photograph of what was behind the wall.
- Same day it is needed. No waiting on a third-party estimating service to fit your loss into their queue.
- Written by people who were in the room. The crew that took the moisture readings is the crew whose findings go into the scope — which is also why a supplement for hidden damage can be put together the day demo uncovers it.
- Within our lane, and we say where it ends. We are your contractor and documentation advocate, not a licensed public adjuster. We do not negotiate or settle your claim for a fee on your behalf — we document the loss and argue the scope.
One contractor, extraction through rebuild
The standard arrangement in this industry is two companies: a mitigation crew dries the structure and leaves, and a rebuild contractor you have to find, vet and schedule puts it back. The gap between them is where projects sit for weeks and where accountability disappears, because each company can point at the other. Raging Bull is a licensed and insured general contractor that does wet demo and remodel-grade finishes, so both halves are one contract.
- One scope, start to finish. The rebuild is priced against the same documented loss as the mitigation, so there is no second estimate that mysteriously exceeds what the carrier allowed.
- One phone number. The same people through drying, demo, the claim, the finishes and the walkthrough at the end.
- Finishes done by remodelers. Hand-matched texture, tile, cabinets and paint from the crew that does bathroom remodels for a living. Restoration work should be invisible when it is finished.
One exception we state plainly: mold remediation itself is performed by licensed mold remediators we coordinate. We find and fix the water source, handle the demo and the structural drying, and stay the single responsible contractor through clearance and the rebuild. See mold remediation & restoration.
The first 24 hours — six moves that protect your home and your claim
What you do before the crew shows up decides how much gets saved — and how much your carrier pays. Wondering where the water came from? Start with the slab-leak warning signs every San Antonio homeowner should know.
Stop the water
Main shutoff first — it's usually at the meter box by the curb or where the line enters the house. Every minute of flow is more drywall gone.
Kill power to wet rooms
If water reached outlets, cords, or the panel wall, shut off those breakers before you step in.
Photograph everything first
Before you mop, move, or tear anything out — wide shots and close-ups. Your claim is only as strong as the record; carriers can't shortchange what's documented.
Open the claim — commit to nothing
Report the loss to your carrier so the clock starts, but don't accept a scope, a preferred vendor, or a settlement figure on day one.
Move what's dry, leave what's wet
Get furniture and valuables out of the water's path. Leave wet materials in place — they're evidence until they're photographed.
Get drying started within 24–48 hours
Mold doesn't wait for the adjuster. Extraction, air movers, and dehumidifiers inside the first two days is what keeps a water loss from becoming a mold job.
Who's paying changes the whole answer
Restoration pricing splits cleanly in two, and almost every “what does this cost” article online ignores the split. A small loss you handle yourself and a loss your carrier pays for are not the same job priced differently — they are priced by two different people, in two different systems.
You're paying out of pocket
A single room caught early — a supply line under a sink, a water heater that let go while someone was home — often is not worth a claim at all, because the deductible can be most of the job. For losses that size we quote a flat number before equipment goes through the door, and it does not move unless the scope does.
What actually moves the number
- How many rooms the water reached, and what it crossed — tile, carpet, or wood.
- Whether the subfloor is wet. This is the big one: a wet subfloor is the difference between drying a room and rebuilding one.
- Whether drywall and insulation have to come out, or can be dried in place with the wall opened low.
- How many days the air movers and dehumidifiers have to run before the moisture readings say dry.
- The category of water — clean supply line, grey water, or sewage — which decides what can be saved and what has to go.
- What the rebuild actually is: paint and baseboard, or flooring, cabinets, and tile.
Call (512) 665-1073 and describe what happened — you'll get a real number on the phone, not a “we'd have to come look at it.” If we can't price it honestly without seeing it, we'll say that too.
Insurance is paying
Then the price isn't ours to set — and you should be wary of any contractor who hands you one. Insurance losses are priced in Xactimate, the estimating platform your adjuster uses. We write our estimate in the same software, at the same unit prices, so our scope and theirs line up line for line instead of arguing past each other.
What you pay is your deductible. The rest is between the policy and the estimate — which is exactly why the fight is over scope, not price. Is the wet subfloor in the estimate? Does the whole room get painted, or just the patch? Does the supplement go in when demo opens a wall and finds more? Those lines are where a claim is won or lost, and arguing them is our job, not yours.
Whether to file a claim at all is between you and your agent — deductibles, premiums, and your own claim history are their conversation to have with you. We'll explain honestly how each path works and leave the decision where it belongs.
The adjuster calls come to us
The part nobody warns you about isn't the cost — it's the phone. The adjuster wants measurements. Then photos of the back wall, by six o'clock. Then a question about what's under the flooring. Handled by a homeowner between work and dinner, that is how a claim quietly shrinks.
We take that off you: the estimate, the scope disagreements, the supplements, the photos on demand. The same person who answers the phone at two in the morning is the one who talks to your adjuster at two in the afternoon.
Timeline is a different question from price
Structural drying is typically 2–4 days whoever is paying. The equipment runs until the moisture readings say dry, not until the calendar says so — and that part does not speed up or slow down based on who is writing the check. The rebuild after it is what varies with scope.
An insurance job doesn't take longer because the work is slower. It takes longer because approvals sit between the steps — and the only thing that shortens that is documentation good enough that there's nothing left to argue about.
Your insurance company has an adjuster. Now you have one on your side.
When you file a claim, your carrier sends an adjuster whose job is to close the loss for as little as the policy allows. Most homeowners face that alone — and settle for a check that never covers the real damage. Not with Raging Bull. Our in-house insurance department goes to work for you: we document every dollar of damage, write the scope in the carrier's own software, and fight to get your claim paid for what it actually takes to rebuild.
We DocuSketch every loss
A full 3D scan and measured floor plan of your property, captured before demo. Hidden and secondary damage goes on the record — and an adjuster can't shortchange what's documented.
We submit the supplements
When we open a wall and find damage no one could see from the doorway, we photograph it, add it to the scope, and file the supplement — so it's covered by your carrier, not eaten by you.
You stay our client
First walkthrough to final invoice, we work for you — not the carrier. We don't stop pushing until your home is restored and your claim reflects the full loss.
All carriers. Property managers and adjusters: we already run make-ready and water-damage repairs for one of the largest property management companies in Texas across San Antonio multifamily properties. Direct line for portfolio work: apartment make-ready & unit turns.
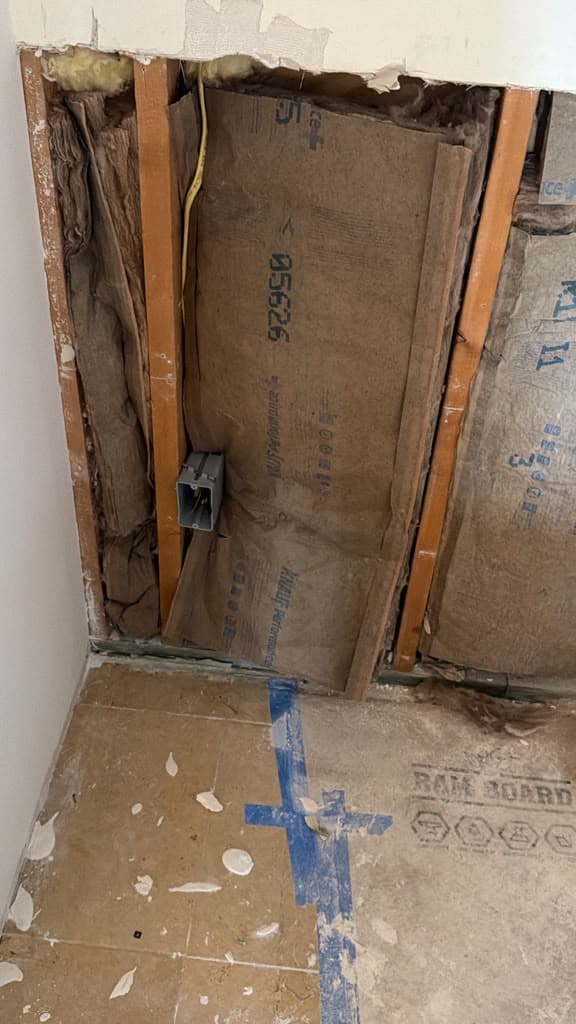
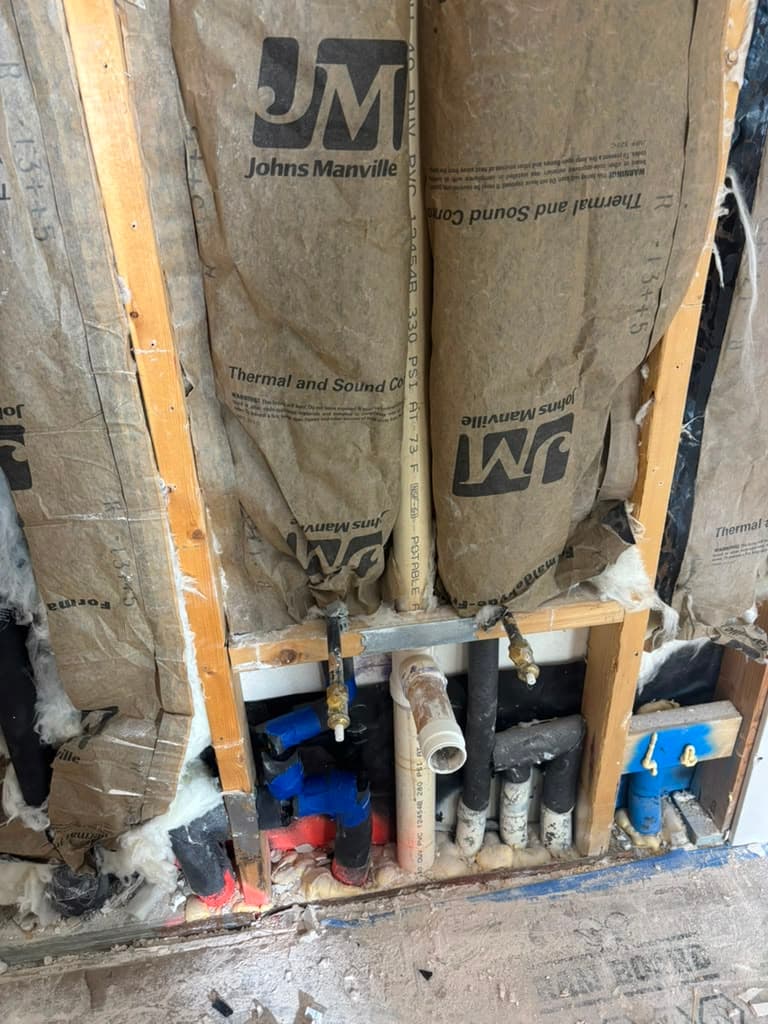
This is what fighting for your claim looks like
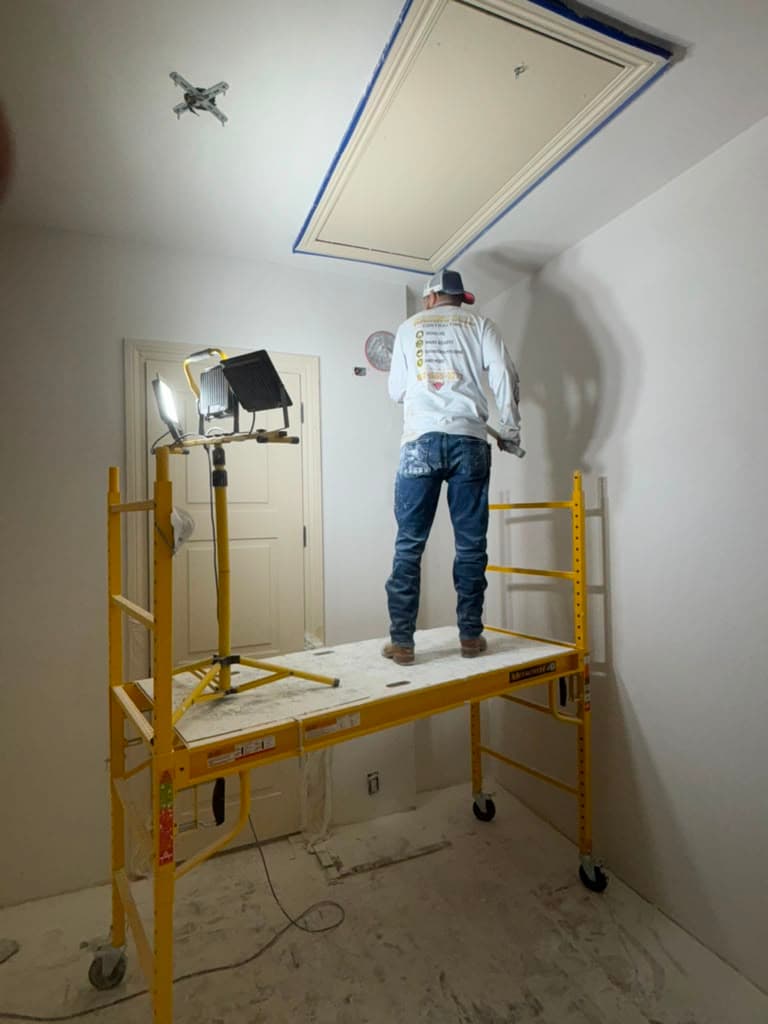
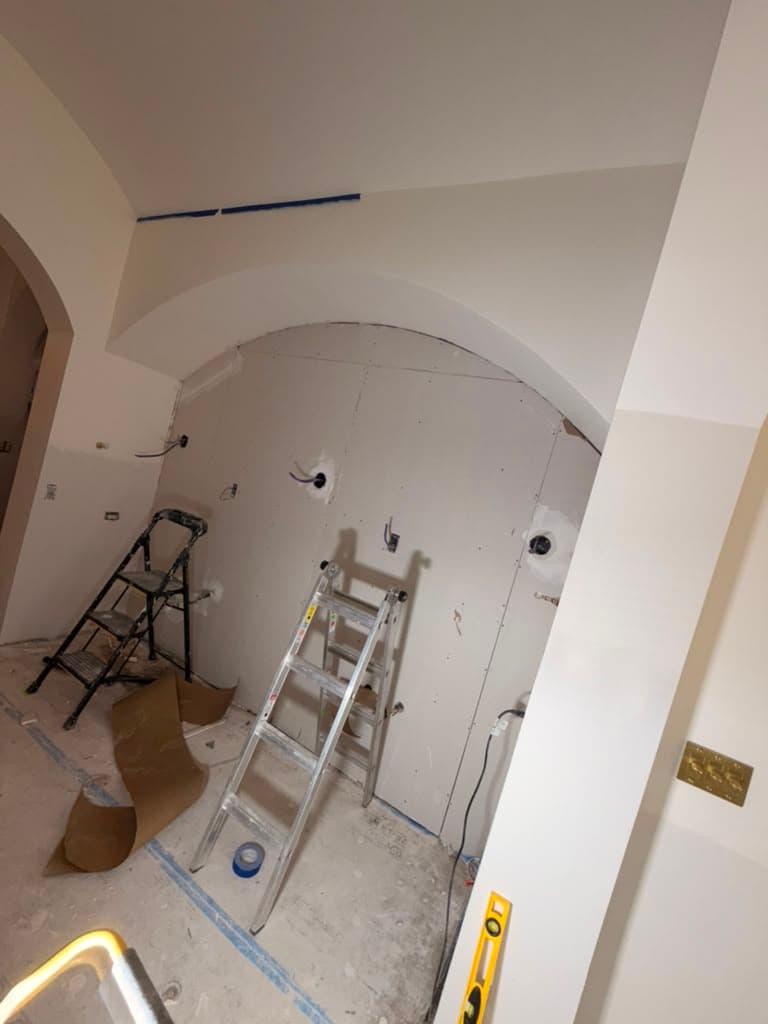
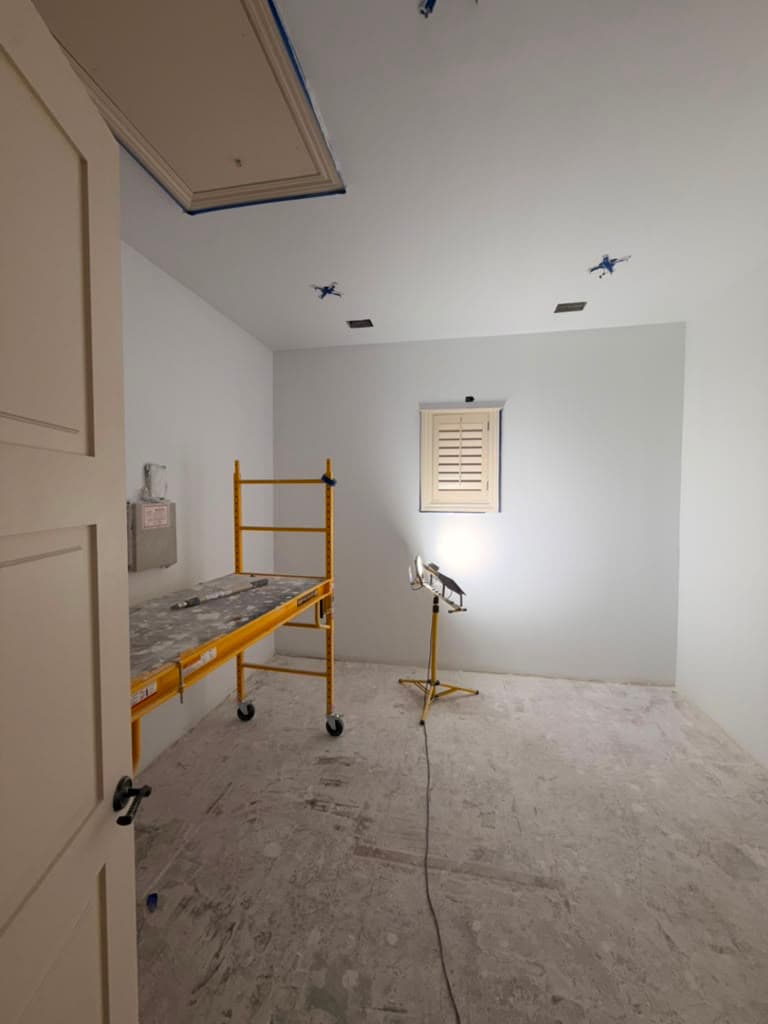
An active San Antonio water-loss restoration. Every opened wall, every foot of wet material, every hidden line is photographed and added to the claim file — the documentation that gets supplements approved and gets you covered in full.
Rebuilt to remodel grade
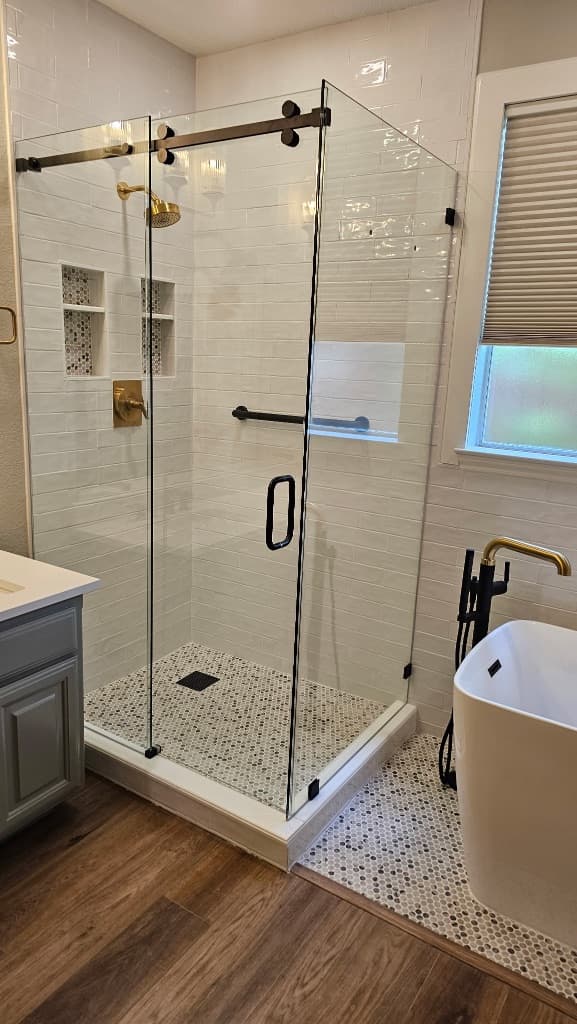
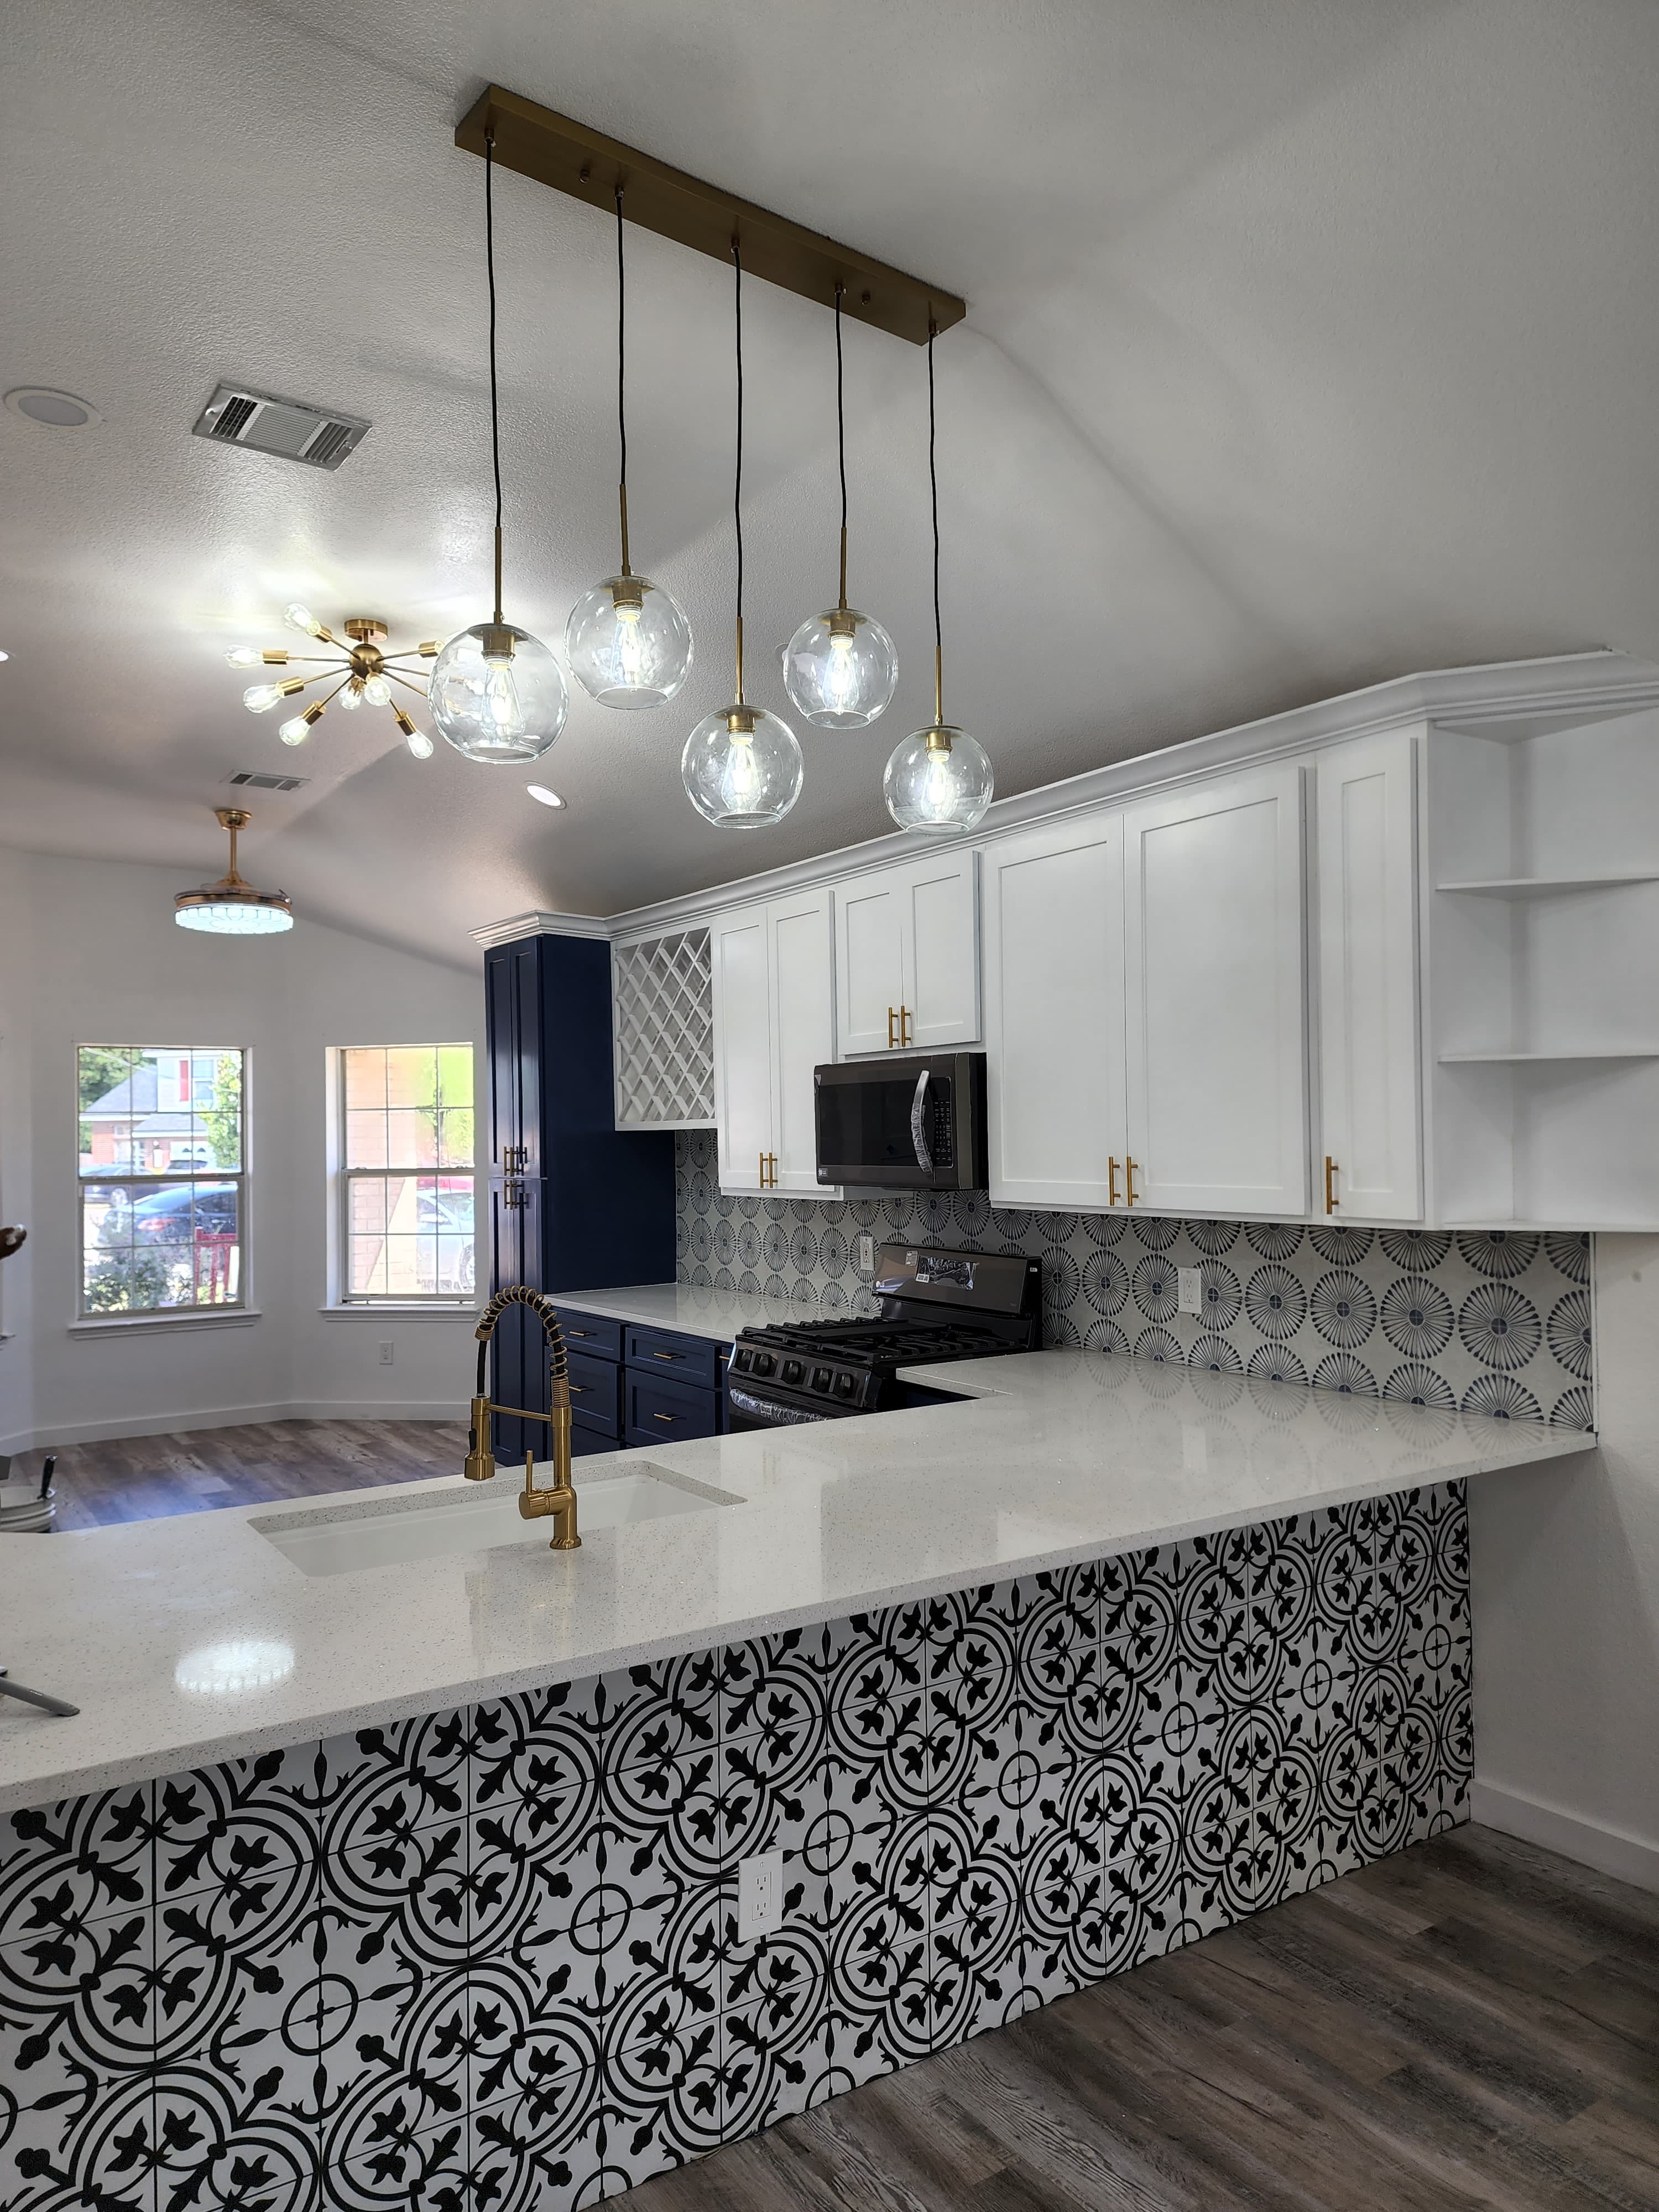
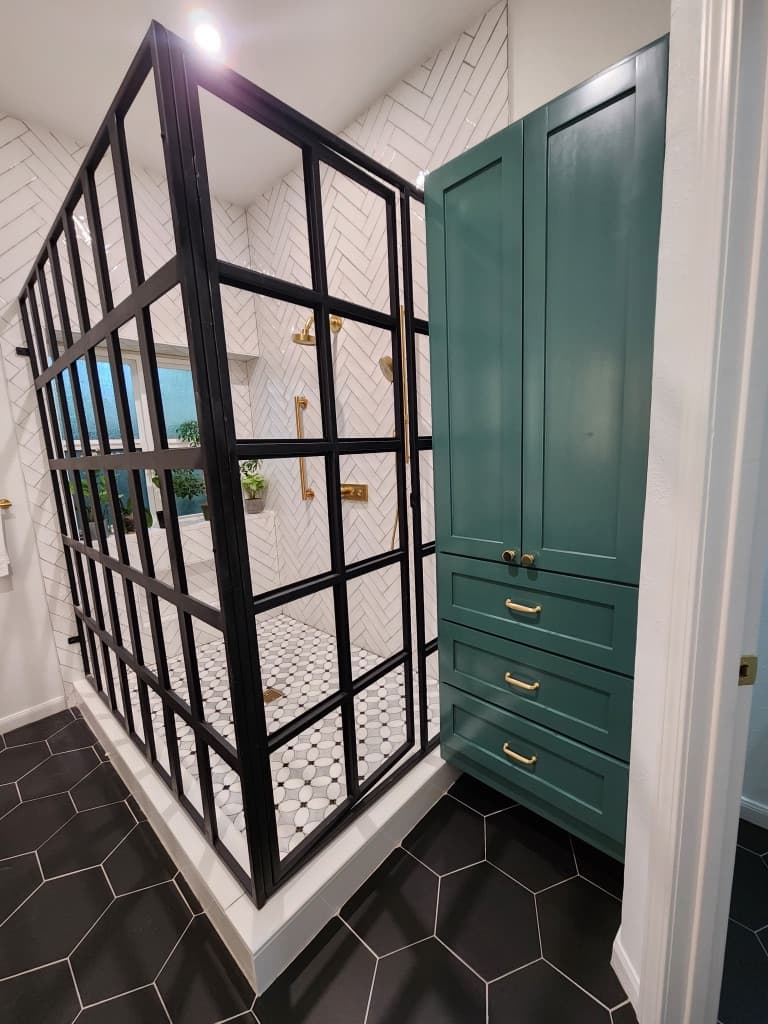
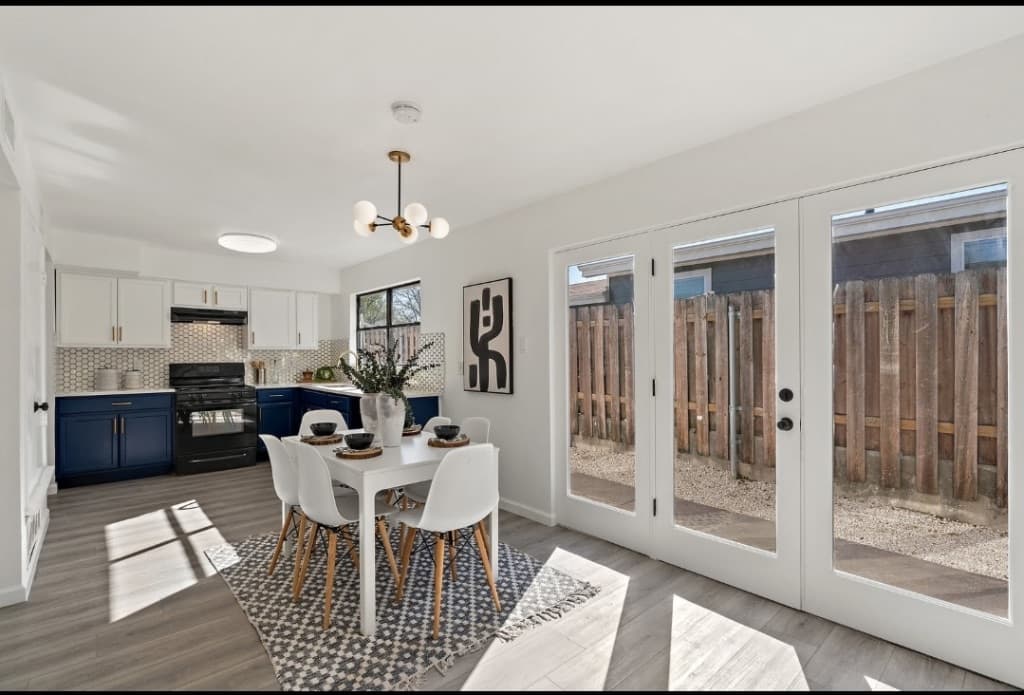
Restoration work should be invisible when it's done — drywall, texture, paint, and flooring that match what was there, or better.
Restoration across Greater San Antonio
Responding to water, fire, and storm losses for homeowners and property managers throughout the San Antonio metro.
- San Antonio
- Alamo Ranch
- Stone Oak
- Northwest Side
- Northeast Side
- Medical Center
- Schertz
- Converse
- Universal City
- New Braunfels
Restoration travels further than remodeling does — a water loss will not wait for a contractor who happens to be closer. We now take water, fire and storm losses down the US-57 corridor and out US-90 to Eagle Pass, Del Rio, Maverick County and Val Verde County, including Uvalde, Crystal City, Carrizo Springs and Brackettville.
Fastest way to start your claim
Call (512) 665-1073 for an active emergency. Otherwise, send your details and we'll reach out to schedule an assessment and start documenting your loss for the claim.
A customer whose roof came down
Raging Bull repaired my closet that the roof caved in due to water damage. The put new padding under the carpet, the did drywall and texturing and painted the whole closet. They were very professional and did an flawless job. They took there time to do it right.
Quoted word for word, spelling and all, from our Google Business Profile — 5.0 stars across 28 reviews. Read every one of them on Google.
Real water jobs, start to finish
Not stock photos, and not a description of what we would do. These are our own jobs — the meter readings, the opened walls, and the finished rooms.
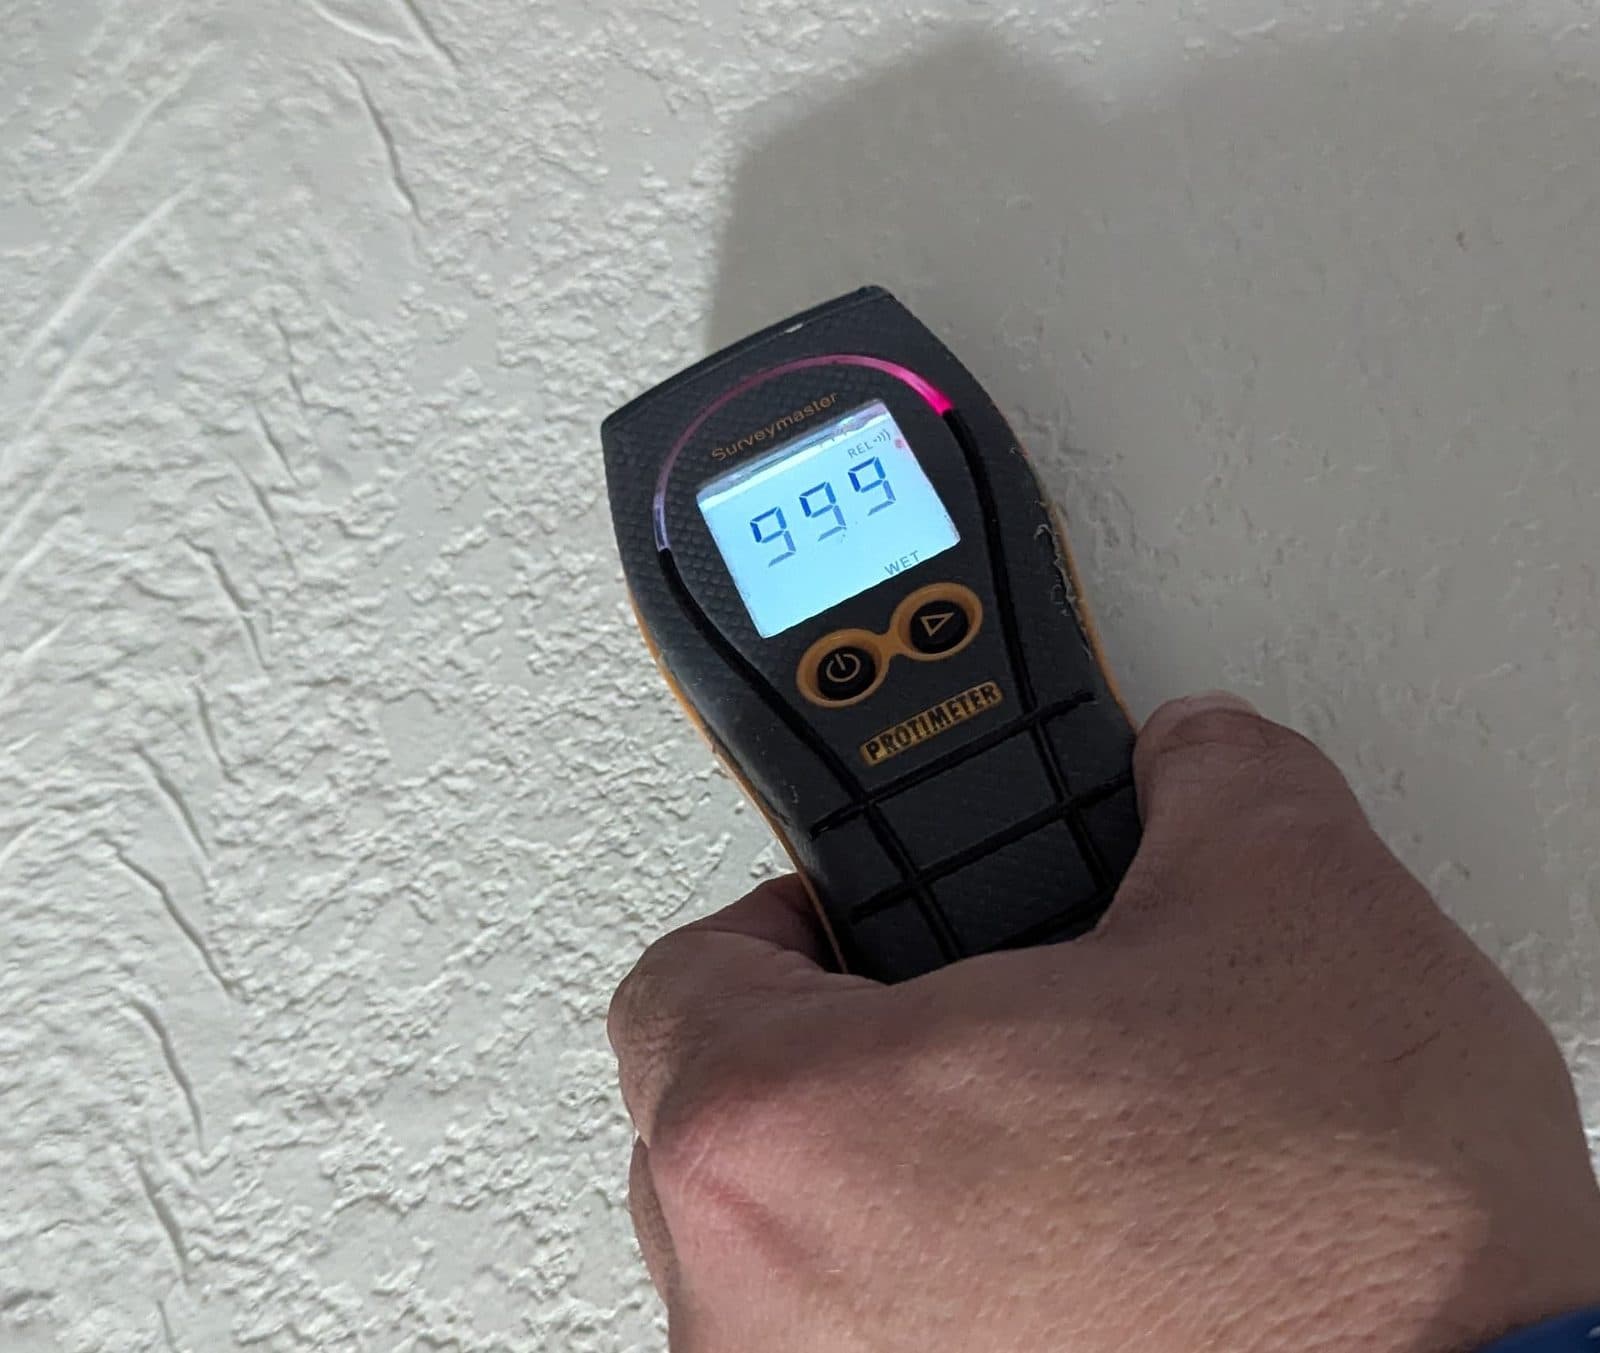
- Cibolo — 999 on the meter, worked the same day
A laundry wall pinned the meter at the top of its scale, and the next room still read wet at 212. Wall opened and drying equipment running before we left that day — then drywall, hand-matched texture, and the room put back. - Sonoma Ranch — a slow shower leak that reached the kitchen ceiling
The opposite failure: no burst pipe, just cracked grout feeding water into the subfloor for months. New subfloor, real waterproofing, full rebuild.
Before you call your carrier, read this
Which water losses a Texas homeowners policy typically covers, which are excluded, what “sudden and accidental” actually means, and the documentation that changes an adjuster's answer. What homeowners insurance covers for water damage in Texas →
Water, fire & storm restoration FAQ
- Yes — 24/7, and it is Rey's own phone. English or Spanish, any hour, any day. To be straight with you about what that means: 24/7 is when the line is answered, not a promise that a crew is standing by at 2am. You will get a real person who can tell you what to do in the next ten minutes, and an honest answer about when we can be on site.
Water in your home right now?
Call now and we'll tell you straight what we can commit to today. Or send the property details and we'll schedule an assessment walkthrough.